HOME BUYING + FINANCING
Let’s Find Out What You Can Actually Buy
See what homes fit your budget, what your monthly payment could look like, and which financing options may make the most sense for you.
Find out what you can actually buy
See which homes fit your budget, what your monthly payment could look like, and which loan options get you there, from one person who handles both the home and the mortgage.
Your home buying plan, in one place
- Your real budget. What you can buy, not just what a lender approves.
- Your monthly payment. Taxes, insurance, HOA, and PMI included.
- Your cash to close. Down payment options from 0% to 20%, plus assistance programs.
- Homes that fit. New and resale homes in the DFW areas you like.
PJ Zaji, REALTOR® TREC #631862 and Mortgage Loan Originator NMLS #2280005, NEXA Mortgage NMLS #1660690.
The price of the home is only part of the decision
You may have already found homes you like. The bigger question is whether the down payment, monthly payment, and cash to close work for you.
Your monthly payment
Principal, interest, taxes, insurance, HOA, and PMI. The number that actually leaves your account.
Your cash to close
Down payment, closing costs, and prepaid items, minus any seller or builder credits.
The home itself
Price, location, schools, and resale. The part most buyers start with.
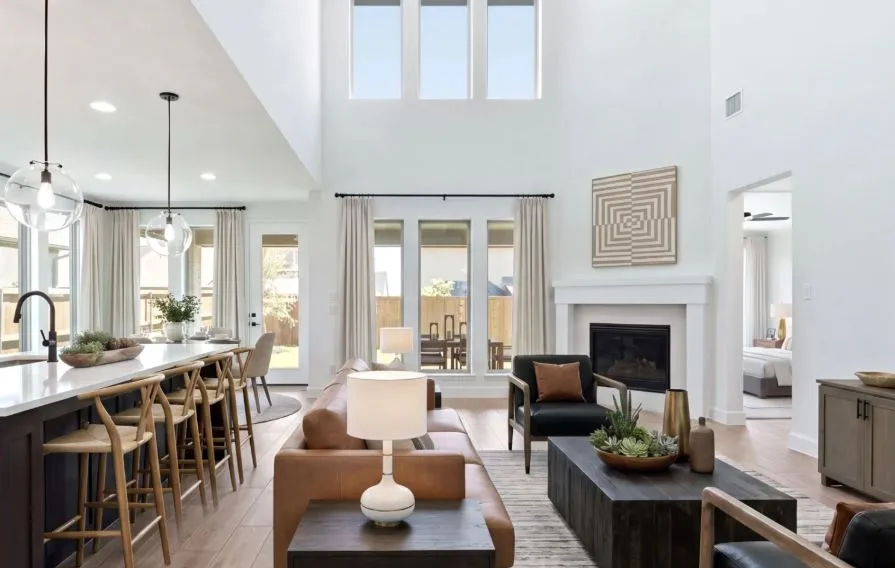
One strategy for the home and the financing
Most buyers search for the home and figure out the mortgage separately. PJ helps you look at both at the same time, so you never fall in love with a home that does not fit your payment.
Ways to buy with less down
PJ shops more than 280 wholesale lenders, so you see every program you qualify for side by side.
Conventional, 3% down
For many first time buyers, with PMI that can be removed later.
FHA, 3.5% down
Flexible credit guidelines and competitive rates.
VA, 0% down
For eligible veterans and service members, with no monthly PMI.
Down payment assistance
Texas programs that can cover part of your down payment or closing costs.
Builder incentives
Rate buydowns and closing cost credits on new construction homes.
Self employed loans
Bank statement and other options when tax returns do not tell the whole story.
Maybe you have told yourself one of these
Each one is worth a real conversation, with real numbers for your situation.
Rates are too high.
Builder buydowns and seller credits can lower your rate today, and you can refinance later if rates fall.
Homes are too expensive.
New construction incentives and negotiable resale homes can bring the payment into range.
I need a bigger down payment.
Many programs start at 0% to 3.5% down, and assistance can help with closing costs.
My payment would be too high.
PJ shows the payment on every home first, so you only tour homes that fit your budget.
Try your own numbers
Move the sliders to see an estimated monthly payment. PJ can turn this into a real quote with your actual rate and program.
Get my real numbersEstimate a DFW payment
- Principal + interest (30-yr)
- $0
- Property tax
- $0
- Homeowners insurance (est.)
- $0
- HOA + PID
- $0
Estimate only. DFW tax rates often run about 2 to 2.5 percent. Insurance estimated at 0.6 percent of price per year. Not a commitment to lend.
You should not have to figure this out alone
Buying a home is not just about finding a property you love. It is also about understanding what you are paying, how you are financing it, and whether the overall deal makes sense. PJ helps you look at both sides before you decide.
- Your budget and payment before you tour
- Loan options from 280+ lenders
- One person from search to closing
Home buying: common questions
How much house can I afford?
It depends on your income, debts, credit, down payment, and the taxes and HOA on the home. Most lenders look at total monthly debts up to about 43 to 50 percent of gross income, but the right budget is the payment you are comfortable with. PJ runs both numbers for you.
How much do I need for a down payment?
Less than most people think. Conventional loans start at 3 percent down for many first time buyers, FHA at 3.5 percent, and VA and some USDA loans at 0 percent. Down payment assistance programs can cover part of the rest.
Should I wait for rates to drop?
Waiting can cost you if prices rise while you wait. Many buyers buy now and refinance later if rates fall. Builder rate buydowns can also lower the rate today. PJ compares both paths with real numbers.
Will checking my options hurt my credit?
Getting started does not require a credit pull. When you are ready for a pre-approval, PJ will explain the credit check before it happens.
Why use one person for the home and the loan?
Because the home and the financing affect each other. PJ can tell you what a specific home will cost each month before you write an offer, and he can negotiate builder incentives toward your rate.
Find out what you can actually buy
Answer six quick questions and PJ will send your budget, payment, and loan options.
PJ Zaji, REALTOR®, TREC #631862, Monument Realty. Mortgage Loan Originator NMLS #2280005, NEXA Mortgage NMLS #1660690. Payment estimates are not a commitment to lend. All loans subject to credit and property approval.
The Price of the Home Is Only Part of the Decision
You may have already found homes you like.
The bigger question is whether the down payment, monthly payment, interest rate, taxes, insurance and overall cost make sense for you.
Before you decide to buy or decide to wait
Let’s look at the complete picture.
One Strategy For The Home & The Financing
Most buyers search for the home and figure out the mortgage separately.
I help you look at both.
As a REALTOR® and mortgage professional, I can help you understand how the home price, negotiations, builder incentives, financing and monthly payment work together.
FIND THE RIGHT HOME
Homes that fit your needs
New construction
Resale homes
Builder incentives
Negotiation
UNDERSTAND NUMBERS
Down payment options
Mortgage Options
Monthly Payment
Closing Cost
Seller Credit
Make A Smarter Decision
Compare Your Options
Understand the real cost
Know what fits you
Decide whether buying now make sense
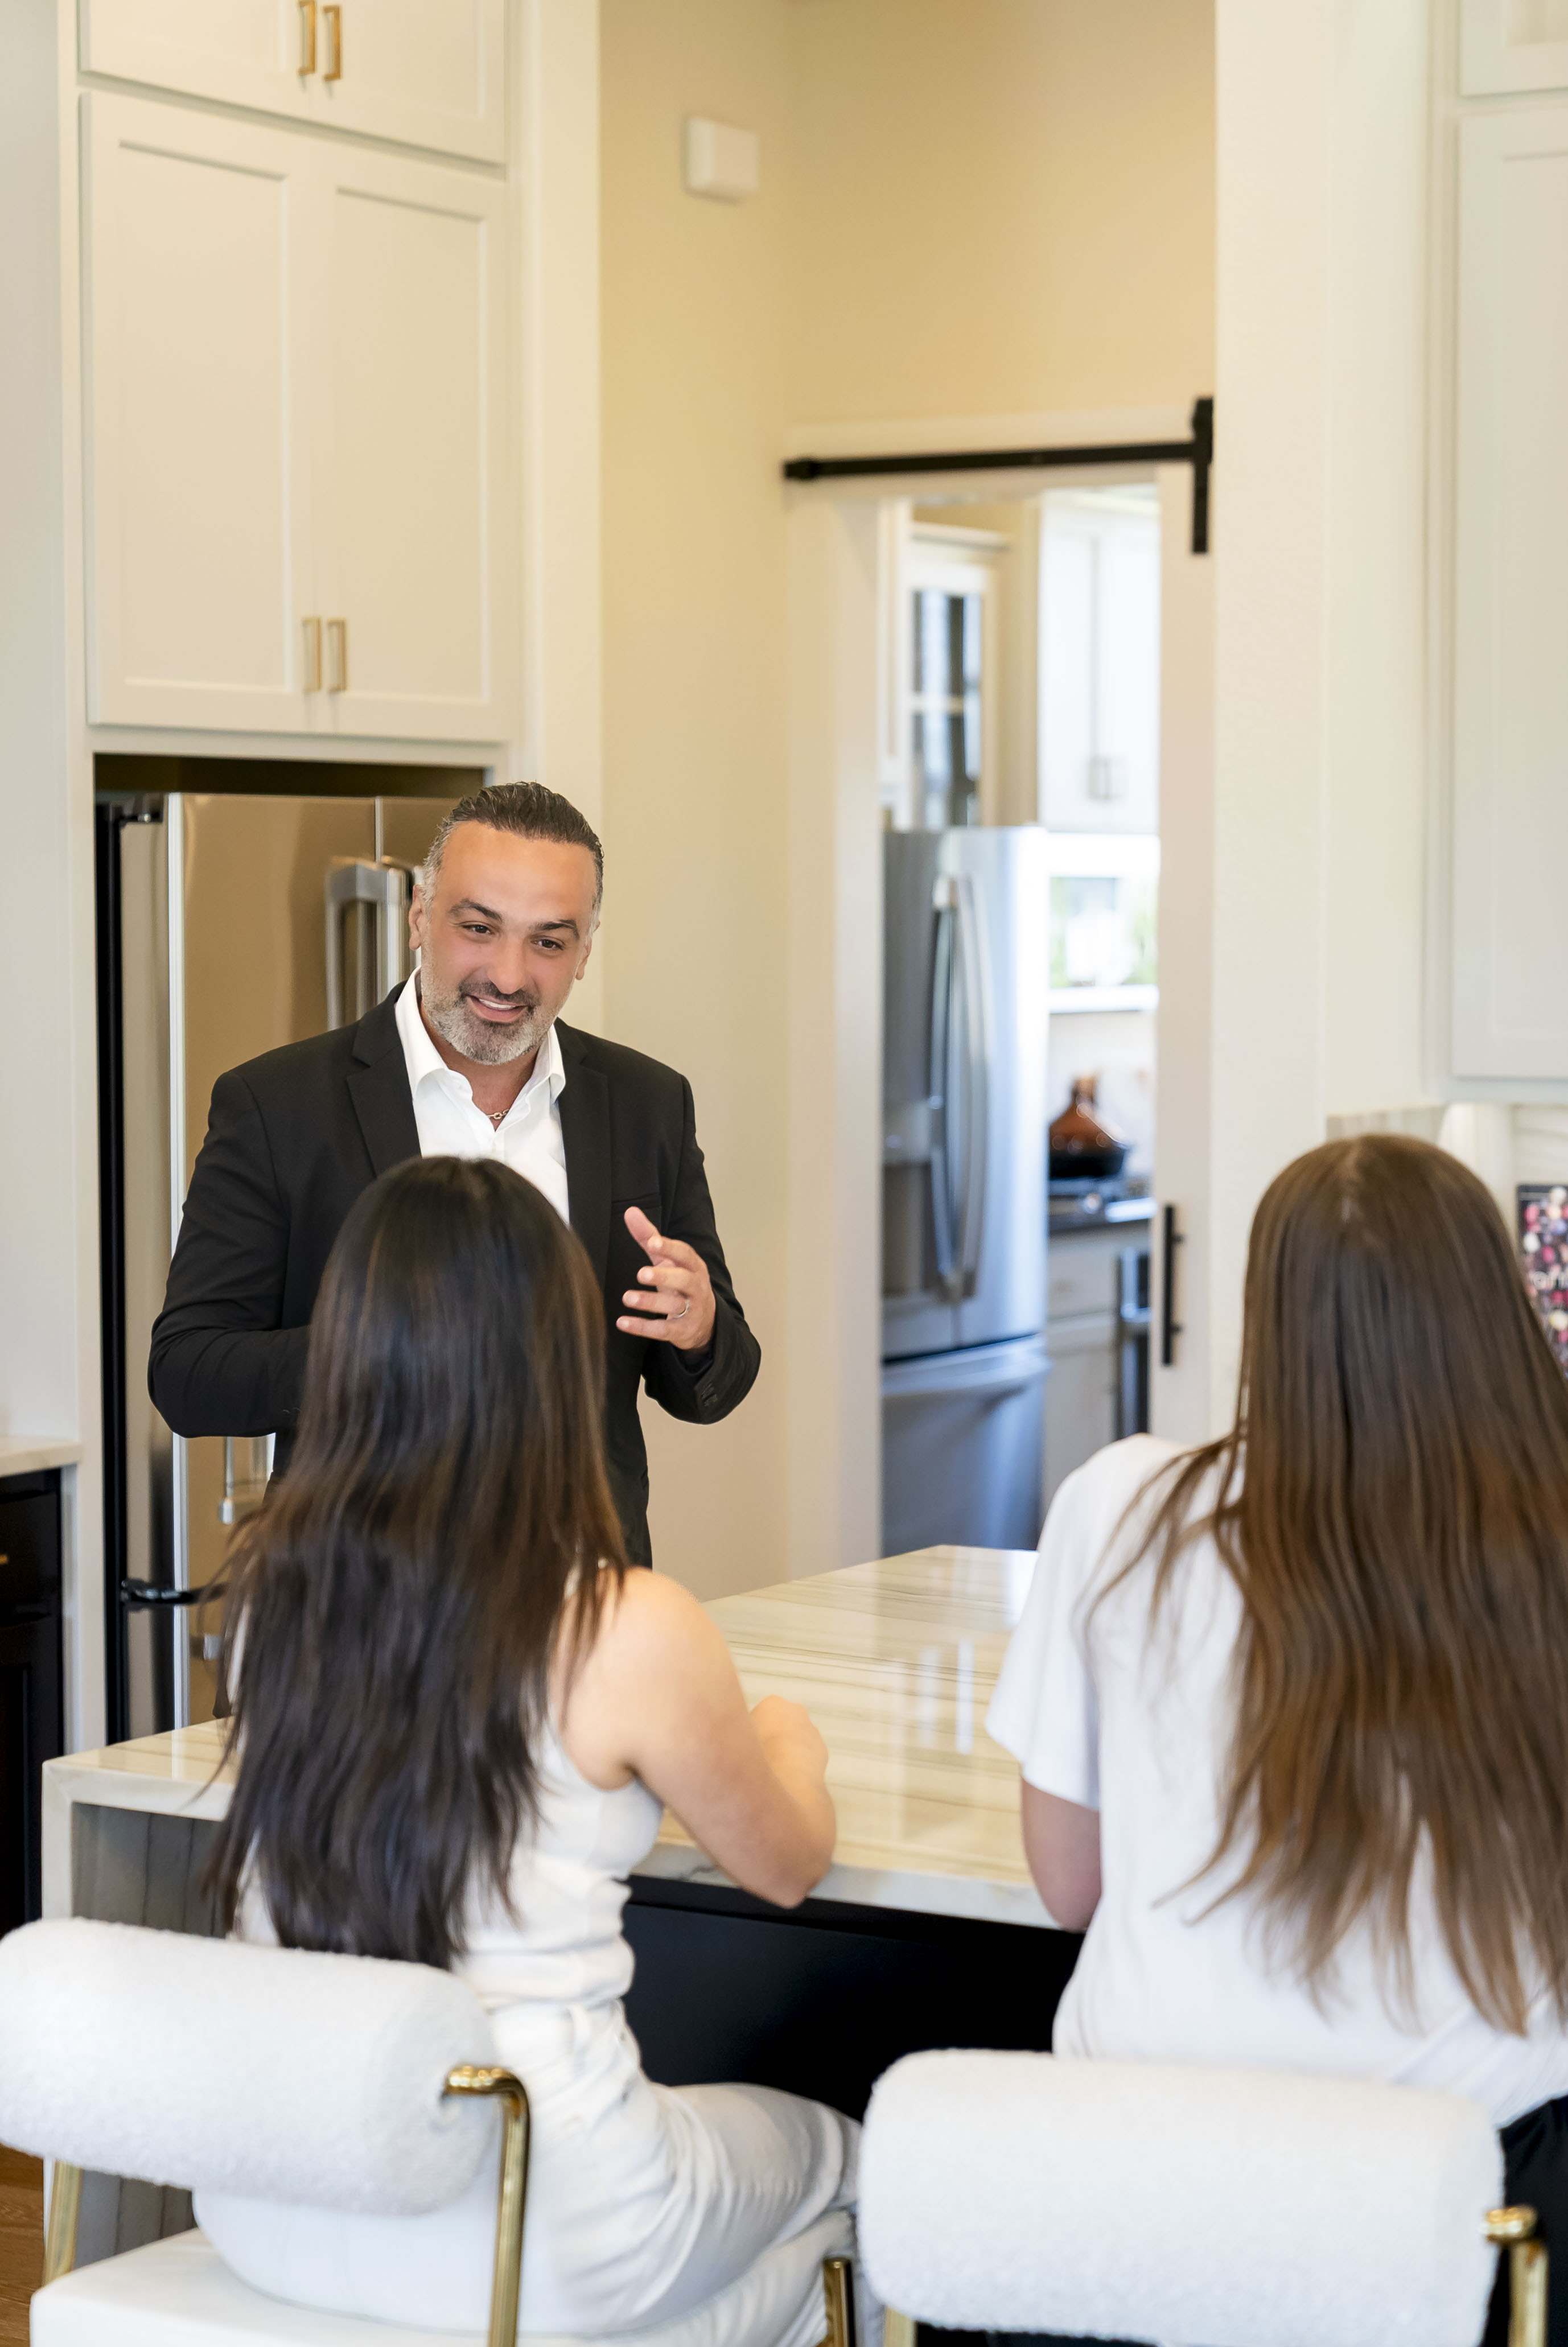
One Strategy For The Home & The Financing
Most buyers search for the home and figure out the mortgage separately.
I help you look at both.
As a REALTOR® and mortgage professional, I can help you understand how the home price, negotiations, builder incentives, financing and monthly payment work together.
FIND THE RIGHT HOME
Homes that fit your needs
New construction
Resale homes
Builder incentives
Negotiation
UNDERSTAND NUMBERS
Down payment options
Mortgage Options
Monthly Payment
Closing Cost
Seller Credit
Make A Smarter Decision
Compare Your Options
Understand the real cost
Know what fits you
Decide whether buying now make sense
Thinking About Waiting?

Maybe you've told yourself:
“Rates are too high.”
“Home prices are too expensive.”
“I need a bigger down payment.”
“My monthly payment would be too high.”
“Maybe I should just wait another year.”
You might be right.
But don't make that decision based on an assumption.
Let’s look at what you could actually buy, what it could cost, and whether buying now makes financial sense for you.
You Shouldn't Have to Figure This Out Alone
Buying a home isn't just about finding a property you love.
It's also about understanding what you're paying, how you're financing it and whether the overall deal makes sense.
I help you look at both sides before you make the decision.