
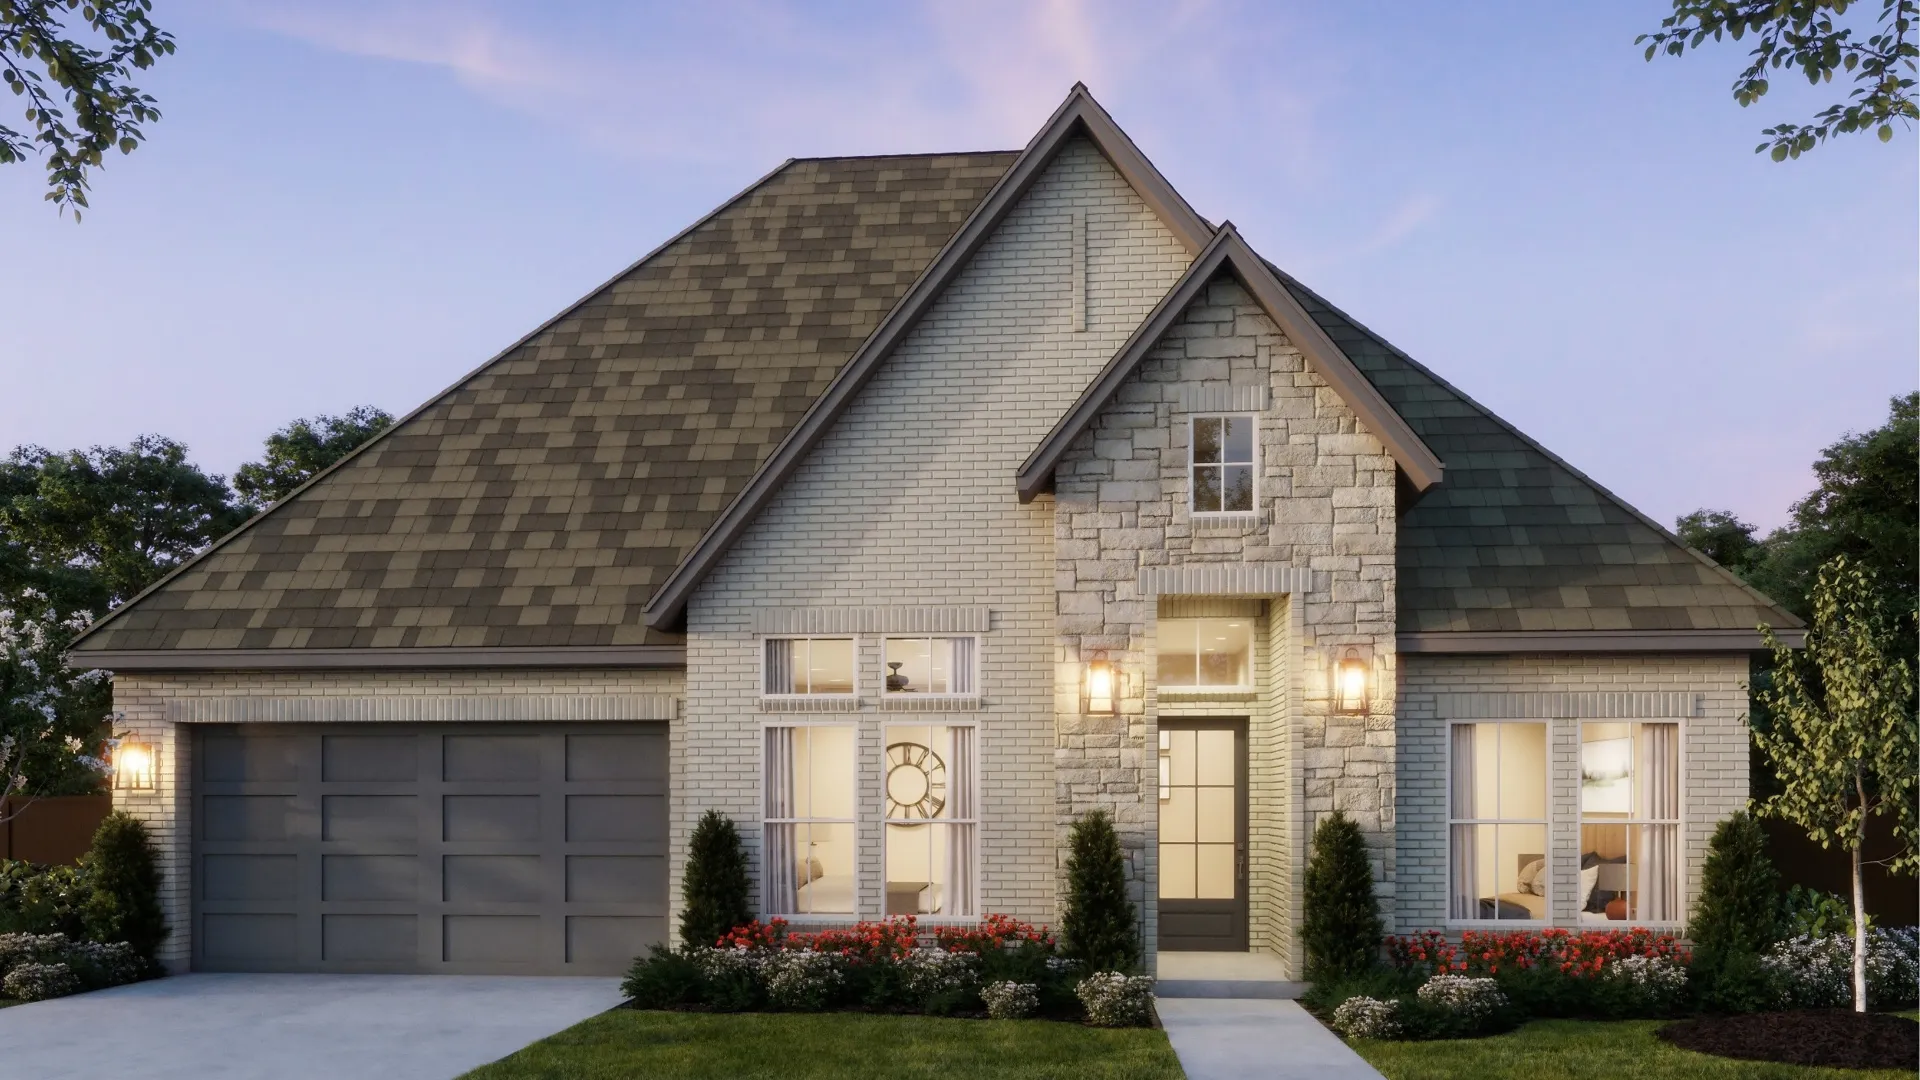
The right home. A plan that makes sense.
Find a home that fits your life, and understand the payment, the tradeoffs, and the next move before you commit. One REALTOR® and loan officer from the first showing to closing day.
Explore the cities, find your fit
 Frisco homes →
 Plano homes →
 McKinney homes →
 Allen homes →
 Prosper homes →
 Celina homes →
 Melissa homes →
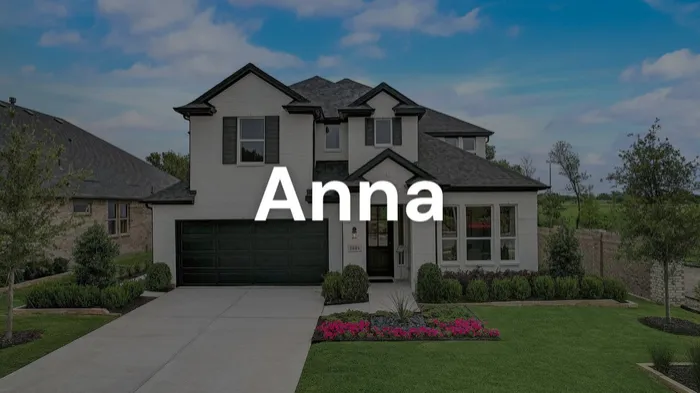 Anna homes →
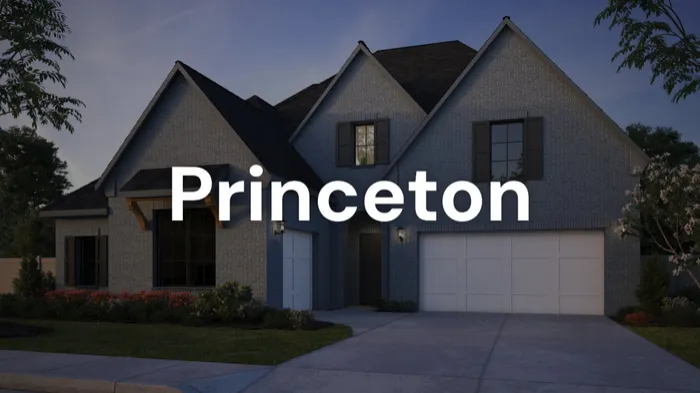 Princeton homes →
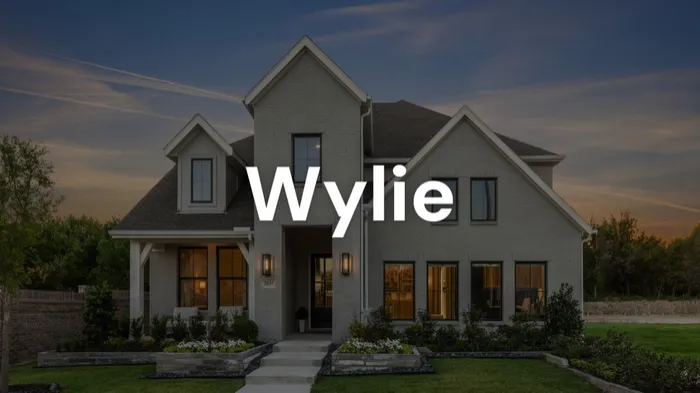 Wylie homes →
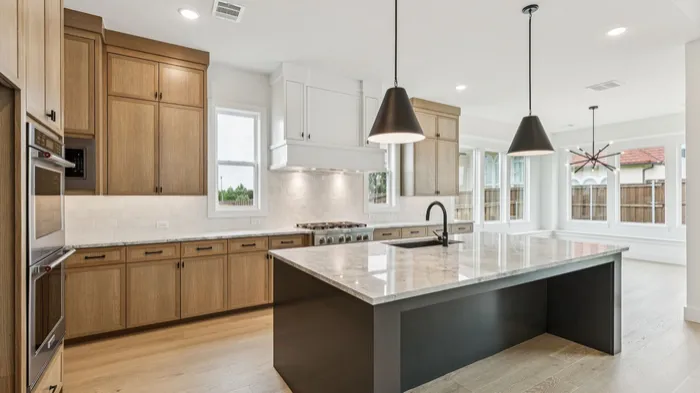
A closer look at what's available
Availability and prices can change. Open any home for current details.
Understand your buying budget
A comfortable purchase starts with the full picture, not just the asking price.
Your monthly ownership cost
Principal and interest, property taxes, insurance, HOA dues, mortgage insurance when it applies, and room for maintenance.
Your cash needed to close
Down payment, lender and title charges, prepaid taxes and insurance, plus inspections and a reserve after the move.
Your financing tradeoffs
Compare rate, points, lender credits, loan term, and builder incentives together. The lowest advertised rate may not mean the lowest total cost.
every offer
What PJ checks before you buy
A beautiful home can still come with expensive surprises. Here's what deserves a closer look.
Condition and inspections
Visible condition, roof and foundation concerns, disclosures, and what an independent inspector finds.
Price and comparable sales
Recent comparable sales, condition, time on market, and the terms that shape a sensible offer.
Taxes and assessments
Tax history, exemptions that may change, and any PID, MUD, or other assessments.
HOA rules and restrictions
Dues, transfer fees, rental limits, architectural rules, and the documents that shape how you use the home.
The everyday fit
Your real commute, nearby services, layout, accessibility needs, and verified school assignments.
Costs after closing
Insurance estimates, utilities, repairs, maintenance, and moving expenses that belong in your decision.
A buying plan for your situation
Buying a home in Dallas Fort Worth should start with your timing, finances, and priorities.
First time buyers
Guidance on preapproval, upfront costs, representation, and what happens at each stage.
Plan My First Purchase →
Relocating to North Texas
Narrow the areas around your commute and lifestyle. Coordinate virtual tours, an in person visit, and your move.
Plan My Relocation →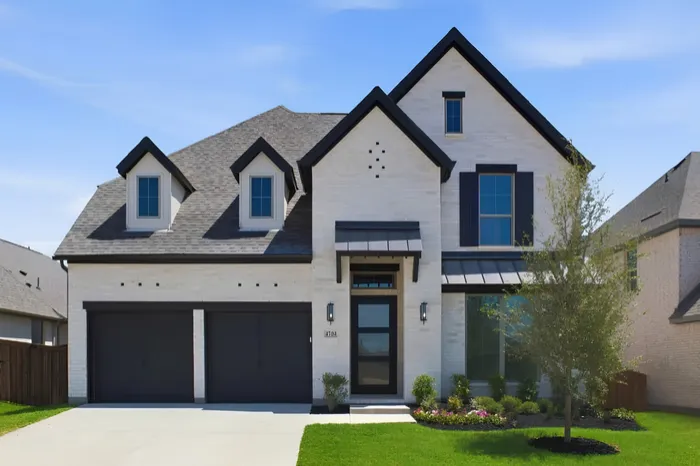
Buying while selling
Compare sale timing, available equity, temporary housing, and contingencies before you commit to the next home.
Coordinate My Buy & Sell →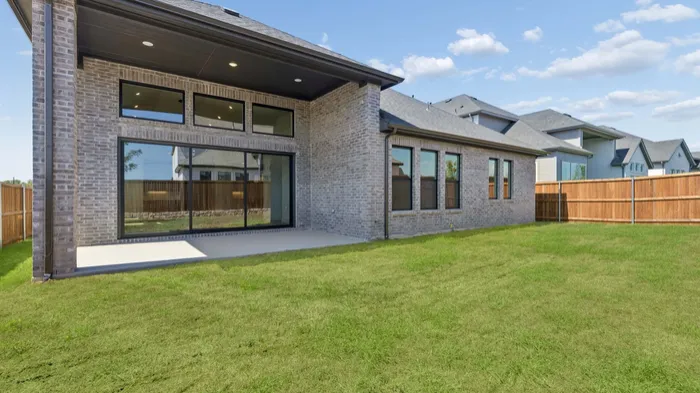
New construction
Compare builders, contracts, incentives, completion timing, and independent inspections.
Compare My Builder Options →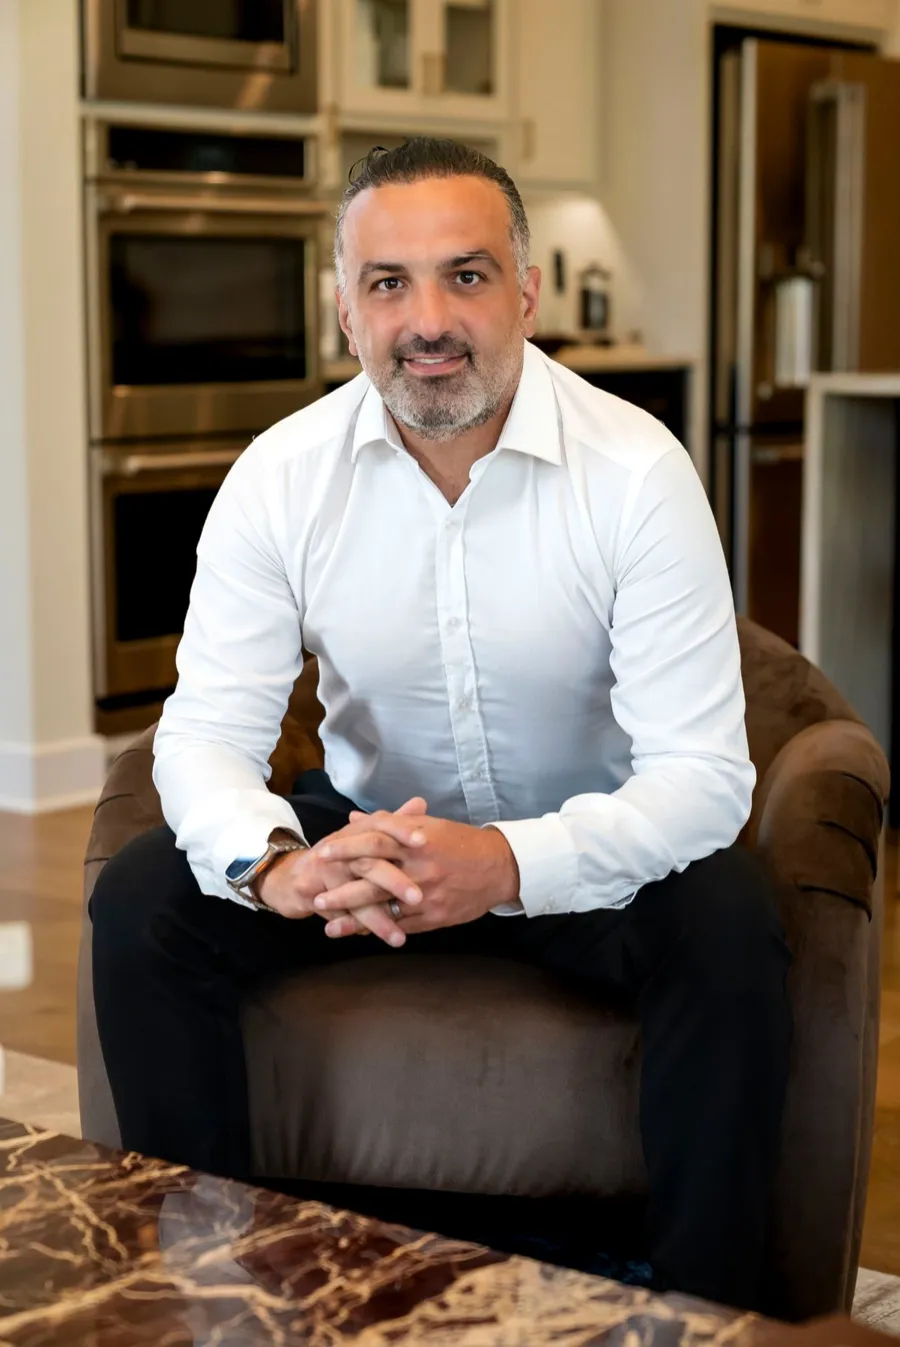
home marketing
PJ Zaji. Homes and numbers, in one conversation.
A home search and a financial decision belong together. PJ's experience in real estate and mortgage lending helps you connect the property, the payment, and the timing of your move.
Expect direct guidance, useful comparisons, and attention to the details before you make an offer. North Texas buyer representation built around your goals.
Their experience. Their words.
Moving to the Dallas area was overwhelming at first, but PJ made the process much smoother. He helped us compare different neighborhoods, understand home values, and narrow down the right areas for our family. His local knowledge and honest guidance made a big difference.
Working with PJ made the home buying process much easier than we expected. He explained every step clearly, helped us understand the market, and never made us feel rushed. From the first showing to closing day, we felt like we had someone experienced on our side who actually cared about getting us the right home.
What stood out most about PJ was how much he cared about doing things the right way. He was honest, responsive, and never pushed us into anything. He gave us the information we needed, explained our options, and helped us make a decision we felt good about.
The home buying process and timeline
 Six clear stages, one point of contact the whole way.
Most financed purchases in Dallas Fort Worth close 30 to 45 days after the contract is signed. Cash can close in as little as 2 weeks.
Plan and preapproval
Set your budget, timing, and must haves. Get preapproved so you know your real price range and monthly payment before you tour.
Search and tour
Compare cities and neighborhoods, tour the strongest homes, and check price against recent sales, taxes, and HOA costs.
Offer and contract
Write the offer on the Texas TREC contract, negotiate terms, and deliver earnest money and the option fee to the title company.
Option period and inspection
Your inspection happens here. You can negotiate repairs or terminate for any reason while the option period is open.
Appraisal, loan, and title
The lender orders the appraisal and finishes underwriting. Title clears the property and the survey is reviewed.
Final walkthrough and closing
Confirm the agreed repairs, review the Closing Disclosure, wire funds securely after verifying by phone, sign, and get your keys.
What it costs to buy a home in Dallas Fort Worth
Budget for more than the down payment. These are the costs buyers see from contract to closing, with typical amounts for a Dallas Fort Worth purchase.
| Cost | Typical amount | When you pay it | Good to know |
|---|---|---|---|
| Earnest money | About 1% of the price, negotiable | At contract, held by the title company | Credited toward your down payment or closing costs |
| Option fee | $100 to $500 | At contract, paid to the seller | Nonrefundable, usually credited to you at closing |
| Home inspection | About $300 to $450 for an average home | During the option period | Larger or older homes, pools, and sewer scopes cost more |
| Appraisal | About $350 to $600 | After the option period, through the lender | Required on most financed purchases |
| Down payment | 0% VA, 3.5% FHA, 3% to 5% conventional | At closing | Jumbo loans usually need 10% or more |
| Lender and title costs | Varies by loan and price | At closing | Your Loan Estimate lists every fee within 3 business days of applying |
| Property taxes | About 1.6% to 2.4% of value per year | Monthly in escrow | Allen 2025 total rate: 1.77%. Varies by city, school district, MUD, or PID |
| Homeowners insurance | Texas average $3,489 per year (2025) | First year paid at closing, then monthly in escrow | Varies by home age, roof, deductible, and location |
Sources: Texas Department of Insurance average homeowners premium (2025, preliminary); HomeAdvisor national inspection and appraisal averages via Rocket Mortgage; Texas option fee and option period norms; Collin County 2025 tax rates. Amounts are typical ranges, not quotes. PJ gives you a written estimate for your price and loan.
Buyer questions, answered
Have a different situation? Let's talk through it.
Should I get preapproved before touring?
It helps establish a realistic budget and shows a seller that you have started the financing process. A lender reviews your finances and explains the conditions. Preapproval is not a guarantee of final loan approval.
How much do I need for a down payment and closing costs?
That depends on the loan, eligibility, property, and negotiated terms. Request a lender's written estimate covering the down payment, closing costs, prepaids, and any applicable credits. Plan separately for inspections and reserves.
How does buyer representation work?
Before touring or signing, discuss the services, agreement term, compensation, and how payment will be handled. Compensation is negotiable, so review the written agreement and any seller contribution rather than assuming the service is free.
Should I buy new construction or resale?
Compare the total cost, location, completion timing, condition, warranty coverage, and contract terms. Builder incentives may have lender or other conditions. New homes also benefit from independent inspections.
Can I buy before selling my current home?
Possibly. A lender needs to assess your ability to qualify and fund the purchase. Compare a sale contingency, available financing options, and the cost of carrying both homes before choosing a sequence.
How do I choose the right area?
Start with your budget, daily commute, preferred home style, and amenities. Visit at different times, verify school boundaries with the district, and compare taxes, HOA rules, insurance, and maintenance costs.
How long does it take to buy a home in Dallas Fort Worth?
Most buyers spend 2 to 6 weeks searching. Once the contract is signed, a financed purchase usually closes in 30 to 45 days and a cash purchase can close in about 2 weeks. Preapproval before you tour keeps the timeline short.
What is the option period in Texas?
It is a negotiated window, typically 5 to 10 days, that starts when the contract is signed. You pay the seller an option fee, usually $100 to $500, and you can terminate for any reason during that window. Inspections and repair negotiations happen here.
Make the next home the right move.
Tell PJ where you want to be, what you want to spend, and when you want to move. Build a practical plan around the home, and the numbers.
